

Table of Contents
A State Pension forecast estimates how much State Pension you could receive, when you may claim it and whether there are ways to increase it. However, the figure is not guaranteed and may change as you gain more National Insurance qualifying years or pension rules are updated.
Checking your forecast can reveal whether you are heading towards the full rate, but interpreting the result is not always straightforward.
Pre-2016 contributions, contracting out, missing National Insurance credits and time spent abroad can all affect the calculation.
You can check your State Pension forecast online through the GOV.UK service or HMRC app. Postal and telephone options are also available for eligible users.
The forecast normally shows:
- How Much State Pension You Have Built Up So Far
- How Much You Could Receive At State Pension Age
- When You May Become Eligible
- Whether You Can Increase Your Forecast
- Which National Insurance Years May Be Incomplete
The full new State Pension is £241.30 a week in the 2026/27 tax year. However, receiving the full amount is not automatic, even if you have 35 qualifying years.
Last Updated: 07.09.2026
What Is The Current UK State Pension In 2026/27?
The amount someone receives depends on whether they qualify under the new or basic State Pension system and their individual National Insurance record.
| State Pension Information | 2026/27 Amount |
| Full New State Pension | £241.30 A Week |
| Four-Weekly Equivalent | £965.20 |
| Annual Equivalent | £12,547.60 |
| Full Basic State Pension | £184.90 A Week |
| Class 3 Voluntary NI Rate | £18.40 A Week |
| Standard New State Pension Minimum | 10 Qualifying Years |
| Standard Post-2016 Requirement For Full Rate | 35 Qualifying Years |
The four-weekly figure reflects the usual State Pension payment cycle. The annual amount is an equivalent based on 52 weekly payments.
People who reached State Pension age before 6 April 2016 normally receive the basic State Pension. Those reaching State Pension age on or after that date generally come under the new State Pension system.
Some people receive less than the standard full rate, while others receive more because they built up protected rights under the previous system.
What Does A State Pension Forecast Show?
A State Pension forecast provides an estimate based on information currently held by HMRC and the Department for Work and Pensions.
It may show:
- Your State Pension Age
- Your Estimated Weekly, Monthly And Annual Amounts
- The Pension Earned From Your NI Record So Far
- The Maximum Amount You Could Potentially Receive
- Whether Additional Qualifying Years Could Increase It
- Gaps In Your National Insurance Record
The amount already built up and the forecast at State Pension age can be different. The first is based on the qualifying history recorded so far. The second may assume that you continue earning qualifying years until State Pension age.
A forecast does not include money held in workplace pensions, personal pensions or self-invested personal pensions. These are separate retirement arrangements.
How Has the State Pension Forecast Changed From 2025 to 2026?
State Pension forecasts increased in April 2026 because both the new and basic State Pension rates rose by 4.8%. However, the amount shown in an individual forecast still depends on their National Insurance record, pre-2016 pension history and expected future qualifying years.
| State Pension Detail | 2025/26 | 2026/27 | Change |
| Full New State Pension | £230.25 A Week | £241.30 A Week | £11.05 A Week |
| Full New State Pension Annually | £11,973.00 | £12,547.60 | £574.60 |
| Full Basic State Pension | £176.45 A Week | £184.90 A Week | £8.45 A Week |
| Full Basic State Pension Annually | £9,175.40 | £9,614.80 | £439.40 |
| Class 3 Voluntary NI Rate | £17.75 A Week | £18.40 A Week | £0.65 A Week |
| State Pension Age | 66 | Gradually Increasing From 66 To 67 | Transition Began In April 2026 |
The full new State Pension increased from £230.25 to £241.30 a week, while the full basic State Pension rose from £176.45 to £184.90. These are maximum standard rates, so someone with an incomplete or complex National Insurance history may receive less.
Another important change began on 6 April 2026, when the gradual increase in State Pension age from 66 to 67 started. The transition will continue until April 2028. This means a 2026 forecast may show a later claim date than someone expected from older retirement information.
The cost of filling National Insurance gaps also increased. A full year of Class 3 voluntary contributions at the 2026/27 rate costs £956.80, compared with £923.00 at the standard 2025/26 rate.
Before paying, check that the incomplete year will increase the forecast because filling every gap does not automatically produce a higher pension.
How Can You Check Your State Pension Forecast?
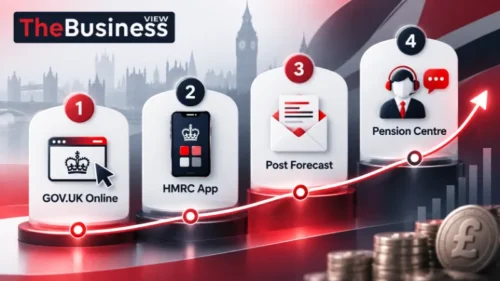
There are several ways to obtain a forecast. The best method depends on whether you can use online services and how close you are to State Pension age.
Check Online Through GOV.UK
The online service is normally the quickest option. You will need to sign in and may be asked to prove your identity using details such as a passport or driving licence.
The basic process is:
- Open The Official State Pension Forecast Service
- Sign In Or Create Sign-In Details
- Complete Any Required Identity Checks
- View The Amount Built Up So Far
- Compare It With The Maximum Forecast
- Review Your National Insurance Record
- Check Whether Any Incomplete Years Can Improve The Result
You do not usually need to prepare your full employment history simply to view the forecast. Employment documents may become relevant if a contribution year appears to be missing or incorrect.
Check Through The HMRC App
The HMRC app provides another way to check State Pension and National Insurance information. It can be useful for people who already use the app to manage their tax details.
The app may allow you to review your forecast and move between it and your NI record without completing a separate postal application.
Request A Forecast By Post
A paper forecast can be requested using form BR19 if you will reach State Pension age in more than 30 days.
The completed form must be sent to the address provided on the application. The posted statement will contain an estimate based on the information available when it is produced.
Contact The Future Pension Centre
The Future Pension Centre can provide assistance to people who are below State Pension age.
It may be particularly helpful when:
- The Online Service Cannot Be Used
- The Forecast Is Difficult To Understand
- Contracting Out Affects The Calculation
- An NI Gap Is Being Considered For Voluntary Payment
- The Person Is Close To State Pension Age
Anyone already receiving State Pension, or who has reached State Pension age and deferred claiming it, should contact the Pension Service instead.
Who Can Use The State Pension Forecast Service?
Most people living in the UK who are below State Pension age can use the online forecast service.
The service cannot normally be used by someone who:
- Is Already Receiving State Pension
- Has Reached State Pension Age And Deferred Their Claim
People living abroad may be able to check online if they already have suitable sign-in details. Others may need assistance from the International Pension Centre.
The service provides a forecast rather than an application. Receiving a forecast does not cause State Pension payments to start automatically.
How Should You Read Your State Pension Forecast?
The forecast may contain several figures that appear similar but mean different things.
| Forecast Information | What It Means |
| Amount Built Up So Far | The estimated pension supported by the NI record currently held |
| Forecast At State Pension Age | The amount you may receive if the stated assumptions are met |
| Maximum Forecast | The highest amount the record may allow you to reach |
| State Pension Date | The date from which you are expected to become eligible |
| Improvement Options | Actions that might increase your entitlement |
| Incomplete Years | Tax years that do not currently count as full qualifying years |
Pay particular attention to the difference between the amount earned so far and the maximum available. If both figures are the same, filling more NI years may not increase the pension.
If the higher figure assumes future contributions, stopping work earlier than expected could leave the eventual pension below the forecast.
How Do Qualifying Years Affect Your State Pension?
A qualifying year is a tax year that counts towards State Pension entitlement. It may be gained through paid National Insurance contributions, contributions treated as paid or National Insurance credits.
People usually need at least 10 qualifying years to receive any new State Pension. These years do not always have to be consecutive.
Someone whose National Insurance record began after April 2016 generally needs 35 qualifying years to receive the full new State Pension.
The calculation can be different when the record began before April 2016.
In these cases, the pension may depend on:
- Contributions Made Under The Previous System
- Additional State Pension Entitlement
- Periods Of Contracted-Out Employment
- The Starting Amount Calculated In April 2016
- Qualifying Years Added After April 2016
This means 35 years does not guarantee the full amount for everyone. Some people with more than 35 years can still receive less, while protected rights can result in others receiving more than the standard rate.
Why Is Your State Pension Forecast Lower Than Expected?
A low forecast does not always mean HMRC has made an error. Several different factors may explain the result.
Gaps In Your National Insurance Record
Periods of low earnings, unemployment, living abroad or not claiming an eligible benefit can create incomplete years.
A year may also appear incomplete if a person worked for only part of the tax year or did not earn enough for it to qualify.
Contracting Out Before April 2016
Many workplace pension members were previously contracted out of the Additional State Pension. This was common in public sector and defined benefit schemes.
During contracted-out employment, the employee and employer generally paid lower National Insurance contributions. The workplace pension was expected to provide part of the retirement benefit instead.
Consequently, someone can have a long NI history but still have a State Pension starting amount below the full new rate.
A Pre-2016 Starting Amount
When the new State Pension was introduced, the government calculated a starting amount for people with contributions under the old system.
The calculation broadly compared entitlement under the old and new rules and used the higher result. Qualifying years gained after April 2016 may then increase a starting amount below the full rate, subject to the applicable limit.
Missing National Insurance Credits
NI credits may protect the record during periods when a person is not paying contributions through work.
Credits may be available in circumstances involving:
- Child Benefit
- Carer’s Allowance
- Carer’s Credit
- Universal Credit
- Jobseeker’s Allowance
- Employment And Support Allowance
- Statutory Maternity, Paternity Or Adoption Pay
- Specified Adult Childcare
Eligibility depends on the individual circumstances and benefit rules. Some credits are applied automatically, while others must be claimed.
Time Spent Living Or Working Abroad
Periods abroad may leave gaps in the UK record. Contributions made in certain countries can sometimes help someone satisfy minimum eligibility requirements, depending on the relevant coordination or social security agreement.
However, the UK pension amount is generally linked to the qualifying UK record. People who have worked in several countries may also be entitled to separate pensions from those countries.
Recent Contributions Not Yet Added
Recently completed tax years or corrected contribution records may not appear immediately. Check the record again after HMRC has processed the relevant information before assuming the contribution has been lost.
What Are Starting Amounts, COPE And Protected Payments?
These terms are especially important for people who paid National Insurance before April 2016.
A starting amount is the value of State Pension entitlement calculated when the new system began. It reflects rights built under both the previous and new calculations at that time.
COPE stands for Contracted-Out Pension Equivalent. It is an estimate connected with periods when a person was contracted out. It indicates that part of their retirement income was expected to come through a workplace or private pension arrangement.
COPE is not normally a separate charge taken from an existing pension account. It is also not necessarily the exact amount the workplace scheme will pay.
A protected payment may apply when someone’s starting amount under the old system exceeded the full new State Pension. The excess is paid above the standard full rate and normally increases in line with inflation rather than under every element of the triple lock.
How Can You Check And Correct Missing National Insurance Years?
Do not pay to fill an incomplete year before confirming why it is missing and whether filling it will increase the forecast.
Follow these steps:
- Compare Both Records: Check the forecast alongside the detailed National Insurance record.
- Identify The Affected Tax Year: Note whether it is shown as full, incomplete or still being updated.
- Review Your Circumstances: Consider employment, self-employment, benefits, caring responsibilities and time spent abroad during that year.
- Check For NI Credits: Establish whether credits should have been applied automatically or whether a claim is needed.
- Collect Evidence: Useful documents may include payslips, P60s, benefit letters and self-employment records.
- Contact HMRC: Ask for an incorrect or missing contribution record to be investigated.
- Seek Pension Confirmation: Check whether correcting or buying the year would actually increase the forecast.
- Review The Updated Forecast: Allow time for accepted changes to appear before making further decisions.
An incomplete year is not automatically worth buying. Its value depends on where it sits in the pension calculation and whether the maximum forecast has already been reached.
Should You Pay Voluntary National Insurance Contributions?
Voluntary contributions can help some people increase their State Pension, but they are not suitable in every case.
| Situation | Possible Next Step |
| Forecast Already Shows The Maximum | Additional Payment Is Usually Unnecessary |
| Enough Working Years Remain | Future Contributions May Fill The Shortfall |
| Free NI Credits Are Available | Claim Or Correct The Credits First |
| Buying One Year Raises The Forecast | Compare The Cost With The Expected Increase |
| Contracted-Out History Applies | Obtain Confirmation Before Paying |
| Pension Credit Could Be Affected | Check The Benefit Consequences |
| The Gap Will Not Change The Forecast | Do Not Pay Solely To Make The Record Complete |
How Much Do Voluntary Contributions Cost In 2026/27?
The standard Class 3 voluntary National Insurance rate is £18.40 a week in 2026/27. A full year at that rate costs £956.80.
For someone calculated entirely under the post-2016 rules, one additional qualifying year could add approximately one thirty-fifth of the full rate. Based on the 2026/27 pension, that is roughly £358.50 a year.
That calculation does not apply identically to every record. Tax, Pension Credit, pre-2016 contributions and the maximum entitlement can affect the actual value.
How Far Back Can You Fill NI Gaps?
Most people can normally pay voluntary contributions for the previous six tax years. The deadline for each eligible year is generally 5 April.
The rate charged can depend on which year is being filled. Waiting may result in an older gap becoming unavailable or becoming more expensive to complete.
When Might Voluntary Contributions Not Be Worth It?
Paying may offer little or no benefit when:
- The Maximum Pension Has Already Been Reached
- Future Employment Will Provide Enough Qualifying Years
- Free NI Credits Can Cover The Period
- The Selected Year Does Not Increase The Forecast
- Higher Pension Income Reduces Means-Tested Support
- The Person Has Contracted-Out Years Rather Than Genuine Gaps
Obtaining confirmation before paying is particularly important because voluntary contributions are not automatically refundable simply because they fail to improve the pension.
What Is The State Pension Age In 2026?
The State Pension age is moving gradually from 66 to 67 between April 2026 and April 2028.
It is therefore no longer accurate to say that everyone can claim at 66. People born during the transition period will have a State Pension age of 66 plus a specified number of months.
The legislated timetable currently provides for a further increase from 67 to 68 between 2044 and 2046. However, State Pension age is regularly reviewed and future governments may change the timetable.
A forecast displays the expected claim date based on the law and information available at that time.
Can You Increase Your State Pension In Other Ways?
Paying voluntary contributions is only one possible option.
Build More Qualifying Years
Continuing to work can add qualifying years where the relevant National Insurance conditions are met. Some people may receive a qualifying year through contributions treated as paid, even when they do not directly pay National Insurance.
Claim Missing NI Credits
Credits can protect a record during periods of caring, unemployment, illness or receiving certain benefits. Correcting missing credits should generally be considered before making a voluntary payment.
Correct Errors In Your NI Record
Missing employment contributions or administrative errors may be corrected when suitable evidence is provided. This can improve the forecast without requiring the individual to purchase the year.
Defer Claiming Your State Pension
Under the new State Pension rules, delaying a claim increases the eventual weekly amount by 1% for every nine weeks of deferral. This is just under 5.8% for a full year.
Deferral is not automatically profitable. The person gives up payments during the delay and may need to live for several years before the higher rate recovers that lost income. Tax and benefit entitlement should also be considered.
What Is The Difference Between A Forecast And An NI Record?
These services provide different information and should not be treated as interchangeable.
| Record Or Service | What It Shows |
| State Pension Forecast | Estimated pension, claim date and potential increases |
| National Insurance Record | Full, incomplete and qualifying tax years |
| Workplace Pension Statement | Benefits or savings held in an employer scheme |
| Personal Pension Statement | Value and projections for an individual arrangement |
| State Pension Claim | The application needed to begin payments |
A complete NI record can still produce a pension below the standard full rate because of pre-2016 calculations. Similarly, a visible gap may not affect the pension if the maximum entitlement has already been achieved.
How Does Working Abroad Affect Your State Pension Forecast?
The effect depends on where the person worked, how long they were abroad and whether the UK has a relevant agreement with that country.
Overseas contribution periods may sometimes help someone reach the minimum qualifying requirement. However, the UK generally calculates and pays its share using the UK National Insurance record.
People approaching retirement after working abroad should check:
- Whether The Overseas Years Appear Correctly
- Whether A Social Security Agreement Applies
- Whether A Separate Overseas Pension Must Be Claimed
- Whether Voluntary UK Contributions Are Permitted
- Whether Their UK Pension Will Increase Annually Abroad
UK State Pension uprating is not available in every country. A person moving abroad should check the rules for their destination before relying on future annual increases.
Is The State Pension Forecast Guaranteed?
No. A State Pension forecast is an estimate rather than a guaranteed payment offer.
It can change because of:
- Additional Qualifying Years
- Corrected National Insurance Information
- A Change In Employment Circumstances
- Future State Pension Uprating
- Changes To State Pension Age
- Changes In Pension Legislation
- Different Assumptions About Future Contributions
Reviewing the forecast periodically is sensible, particularly after changing jobs, becoming self-employed, claiming benefits, taking time out for caring or returning from abroad.
Is State Pension Taxable In 2026/27?
State Pension is taxable income, although income tax is not normally deducted directly from the payment.
The full new State Pension is worth £12,547.60 a year in 2026/27. That is only £22.40 below the standard Personal Allowance of £12,570.
A person receiving the full rate may therefore become liable for tax if they also have income from:
- Employment
- Workplace Pensions
- Private Pensions
- Property
- Savings Interest
- Investments
HMRC may collect tax through another pension or employment PAYE code. People with several income sources should consider the total taxable amount rather than viewing the State Pension separately.
What Should You Do After Checking Your Forecast?
After receiving the forecast:
- Compare The Current And Maximum Amounts
- Review Every Incomplete NI Year
- Check Whether Credits Are Missing
- Investigate Any Unexpected Contracted-Out Information
- Confirm Whether Voluntary Payments Would Increase The Pension
- Include Workplace And Personal Pensions In Retirement Planning
- Recheck The Forecast After Any Corrections
- Note The Expected State Pension Date
Keep copies of documents supporting employment, benefits or caring periods in case an NI record needs to be challenged later.
Common State Pension Forecast Mistakes To Avoid
Common mistakes include:
- Assuming 35 Years Guarantees The Full Pension
- Treating Every NI Gap As Worth Buying
- Confusing The Forecast With A Pension Claim
- Ignoring Contracted-Out Employment
- Forgetting To Check For Free NI Credits
- Assuming State Pension Is Tax-Free
- Believing The Forecast Includes Workplace Pensions
- Relying On An Outdated State Pension Age
- Failing To Investigate Missing Recent Contributions
- Paying Voluntary Contributions Without Confirmation
The best result does not necessarily come from completing every visible gap. It comes from understanding which years and actions genuinely affect the forecast.
Conclusion
Checking a State Pension forecast UK provides an important starting point for retirement planning, but the headline figure should not be viewed in isolation. Qualifying years, pre-2016 contributions, contracting out, credits and time abroad can all influence the result.
Compare the forecast with your NI record, investigate unexpected gaps and confirm that a voluntary contribution will increase the pension before paying. Regular checks can help identify errors early and provide a clearer picture of future retirement income.
FAQs About State Pension Forecast UK
Can I Check My State Pension Forecast Without A Government Gateway Account?
You can create sign-in details when using the online service, subject to identity checks. Alternatively, eligible users can request a BR19 postal forecast or contact the Future Pension Centre.
Why Does My Forecast Show Less Despite Having 35 Qualifying Years?
Your record may include pre-2016 contributions or contracted-out employment. These are subject to transitional calculations, meaning more than 35 years may sometimes be required to reach the full rate.
Does Filling An NI Gap Always Increase My State Pension?
No. A gap may not increase the pension if you have already reached the maximum, will gain enough future years or the selected year does not affect your calculation.
How Often Should I Check My State Pension Forecast?
Check it every few years and after major changes such as leaving work, becoming self-employed, taking on caring responsibilities or returning from abroad. Checking more frequently near retirement can help resolve problems sooner.
Can I Get A Forecast If I Already Receive State Pension?
The online forecast service cannot normally be used once payments have begun. Contact the Pension Service for information about an existing State Pension award.
Can My State Pension Forecast Decrease?
It can change if underlying records are corrected, assumptions are no longer met or legislation changes. The displayed amount is an estimate and not a guaranteed payment.
How Long Does A Postal State Pension Forecast Take?
Processing times can vary. Apply well before making retirement or voluntary-contribution decisions, particularly if the forecast may reveal missing National Insurance information.
Does A State Pension Forecast Include Workplace And Private Pensions?
No. It covers State Pension entitlement only. Workplace and private pensions must be checked separately when calculating total retirement income.