

Table of Contents
In the 2026/27 tax year, a basic-rate taxpayer can normally earn up to £1,000 in savings interest without paying tax. The limit is £500 for higher-rate taxpayers, while additional-rate taxpayers receive no Personal Savings Allowance.
People with a low income may also benefit from an unused Personal Allowance and up to £5,000 through the starting rate for savings.
In limited circumstances, someone with no other taxable income could receive as much as £18,570 in savings interest without an Income Tax bill.
| Taxpayer or saver | Potential tax-free interest |
| Basic-rate taxpayer | £1,000 |
| Higher-rate taxpayer | £500 |
| Additional-rate taxpayer | £0 |
| Eligible low-income saver | Up to an additional £5,000 |
| Saver with unused Personal Allowance | Unused portion of £12,570 |
| Interest earned inside an ISA | Tax-free and outside the PSA |
These limits apply to individuals rather than individual savings accounts. Interest from all relevant accounts must therefore be combined when calculating whether an allowance has been exceeded.
Last Updated: 07.09.2026
What Changed Between 2025/26 and 2026/27?
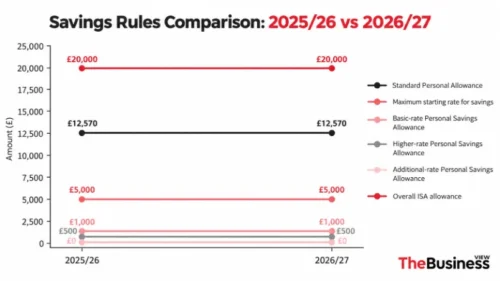
The main tax-free savings allowances have not changed between the 2025/26 and 2026/27 tax years.
However, savers should still use the current tax year when estimating their liability and should be aware of significant changes planned from April 2027.
| Savings rule | 2025/26 | 2026/27 |
| Standard Personal Allowance | £12,570 | £12,570 |
| Maximum starting rate for savings | £5,000 | £5,000 |
| Basic-rate Personal Savings Allowance | £1,000 | £1,000 |
| Higher-rate Personal Savings Allowance | £500 | £500 |
| Additional-rate Personal Savings Allowance | £0 | £0 |
| Overall ISA allowance | £20,000 | £20,000 |
Although the figures remain unchanged, a saver’s position can still be different from one year to the next.
A pay rise, pension increase, larger savings balance or higher interest payment could reduce the tax-free amount available.
What Is the Personal Savings Allowance for 2026/27?
The Personal Savings Allowance, commonly called the PSA, is a 0% tax band that applies to qualifying savings income.
It determines how much interest someone can receive before Income Tax becomes payable.
Interest covered by the PSA is still included in taxable income.
This distinction matters because the interest can affect the taxpayer’s income band, reduce their Personal Allowance or change their eligibility for income-related charges.
Basic-Rate Taxpayers
A basic-rate taxpayer can normally receive up to £1,000 in savings interest during 2026/27 without paying tax on it.
For example, someone earning £30,000 from employment and £800 from taxable savings accounts would not ordinarily owe tax on the interest because it remains within the £1,000 PSA.
If the same person earned £1,300 in interest, £1,000 would be taxed at 0% under the PSA. The remaining £300 would normally be taxed at the basic savings rate of 20%, producing a £60 tax bill.
Higher-Rate Taxpayers
A higher-rate taxpayer receives a reduced PSA of £500. Interest above that amount is normally taxed at 40% during 2026/27.
Someone earning £60,000 from employment and receiving £900 in savings interest would have £500 covered by the PSA. The remaining £400 would normally create a £160 tax liability.
A person close to the higher-rate threshold must include savings interest when determining their tax band.
Interest can push part of their income into the higher-rate band and reduce the available PSA from £1,000 to £500.
Additional-Rate Taxpayers
Additional-rate taxpayers do not receive a Personal Savings Allowance. Taxable savings interest outside an ISA or another exempt product may therefore be taxed from the first pound.
This does not mean every type of savings return is taxable. Interest and investment returns generated within an ISA remain tax-free, while Premium Bond prizes are also exempt from Income Tax.
How Do Tax-Free Savings Allowances Work Together?
Three different allowances can potentially protect savings interest from tax. The amount available depends on how much income the saver receives from employment, pensions, property and other taxable sources.
Personal Allowance
The standard Personal Allowance for 2026/27 is £12,570. A person can use any unused part of it against savings interest.
Someone with no wages, pension or other taxable income could therefore use the full £12,570 Personal Allowance against their interest.
If £10,000 of the Personal Allowance has already been used by a pension, only £2,570 would remain available for other taxable income.
The Personal Allowance begins to reduce when adjusted net income exceeds £100,000. It falls by £1 for every £2 of income above that threshold and is normally removed completely at £125,140.
Starting Rate for Savings
A person with relatively little income from sources other than savings may qualify for a starting rate of 0% on up to £5,000 of interest.
The full £5,000 starting-rate band may be available when other income does not exceed the £12,570 Personal Allowance. It then reduces by £1 for every £1 of other income above the Personal Allowance.
For example, a pensioner receiving £15,000 in pension income has £2,430 of income above the standard Personal Allowance. That reduces the £5,000 starting-rate band to £2,570.
The starting rate is no longer available once other income reaches £17,570.
Personal Savings Allowance
The PSA can apply after the Personal Allowance and starting-rate band. A qualifying basic-rate taxpayer may receive up to another £1,000 of interest at 0%, while a higher-rate taxpayer may receive £500.
The allowances do not need to be claimed separately in routine cases. However, savers remain responsible for checking the interest reported and contacting HMRC if an incorrect amount of tax is collected.
Can You Earn £18,570 in Interest Without Paying Tax?
A person with no wages, pension, rental income or other taxable income could potentially receive up to £18,570 entirely from savings interest without paying Income Tax in 2026/27.
| Tax-free layer | Maximum amount |
| Personal Allowance | £12,570 |
| Starting rate for savings | £5,000 |
| Personal Savings Allowance | £1,000 |
| Potential total | £18,570 |
This maximum does not apply to everyone. Any salary, pension or other income using the Personal Allowance may reduce the amount of savings interest that can be received tax-free.
For example, someone with £14,570 in pension income has already used the full Personal Allowance and exceeded it by £2,000.
Their starting-rate band would fall from £5,000 to £3,000. They may then have a £1,000 PSA if they remain a basic-rate taxpayer.
How Much Can You Have in Savings Before Paying Tax?
There is no fixed savings balance that automatically creates a tax bill. Tax is charged on the interest generated, not on the amount deposited.
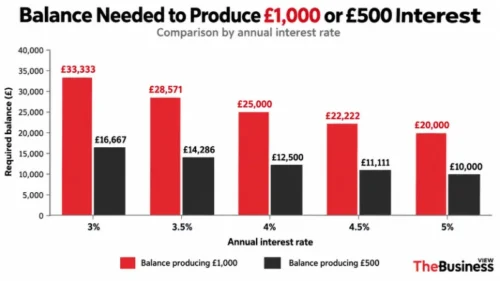
The balance needed to use the full PSA depends on the interest rate. A higher rate means a smaller balance can produce the same amount of interest.
| Annual interest rate | Balance producing £1,000 | Balance producing £500 |
| 3% | £33,333 | £16,667 |
| 3.5% | £28,571 | £14,286 |
| 4% | £25,000 | £12,500 |
| 4.5% | £22,222 | £11,111 |
| 5% | £20,000 | £10,000 |
These figures are simplified estimates. Actual interest can be affected by compounding, variable rates, additional deposits, withdrawals and the date on which the account was opened.
A basic-rate taxpayer with £25,000 in an account paying 4% for a complete year would generate approximately £1,000 in interest.
A higher-rate taxpayer using the same account would reach their £500 PSA with a balance of approximately £12,500.
Can Savings Interest Push You Into a Higher Tax Band?
Savings interest is added to wages, pensions and other taxable income when determining a person’s tax band. This means the interest itself can push someone into the higher-rate band.
Suppose someone earns £50,000 from employment and receives £1,000 in taxable interest.
Their combined income would be £51,000. Part of the income would fall within the higher-rate band, which could reduce the PSA to £500.
The interest covered by the PSA is taxed at 0%, but it is not removed from total taxable income.
It can consequently affect:
- The Taxpayer’s Income Tax band
- The Size of their Personal Savings Allowance
- The Personal Allowance taper above £100,000
- The High Income Child Benefit Charge
- Other Calculations based on adjusted net income
Savers close to an income threshold should calculate their position using total income rather than salary alone.
What Types of Interest Count Towards Your Allowance?
The PSA can cover interest and certain savings-related income from several sources.
| Savings income | Treatment |
| Bank savings accounts | Normally counts towards the PSA |
| Building society accounts | Normally counts towards the PSA |
| Credit union accounts | Normally counts towards the PSA |
| Fixed-rate savings bonds | Normally counts when the interest arises |
| Government and company bond interest | Normally taxable savings income |
| Peer-to-peer lending interest | Normally counts towards the PSA |
| Interest distributions from funds | May count as savings income |
| Foreign savings interest | May be taxable and require separate reporting |
| Trust income received by a beneficiary | Treatment depends on the trust and distribution |
Dividend income does not use the PSA because it is covered by separate dividend tax rules. Capital gains are also subject to their own tax regime.
Government bonds require careful treatment. Interest paid by UK gilts is generally taxable, although gains made when disposing of gilts are normally exempt from Capital Gains Tax.
Are ISAs and Premium Bonds Tax Free?
Interest earned inside a Cash ISA does not count towards the PSA.
The same general tax protection applies to income and gains generated inside Stocks and Shares ISAs, Innovative Finance ISAs and Lifetime ISAs.
The overall ISA contribution allowance is £20,000 for 2026/27.
This is the amount a person can contribute during the tax year, not a limit on the total balance or the amount of tax-free interest that can be earned inside existing ISAs.
Premium Bond prizes are also tax-free and do not use the PSA.
However, ordinary interest paid by many other National&I savings products may still be taxable.
Savers should check the tax status of the specific product rather than assuming every government-backed account is exempt.
Money cannot be moved into an ISA retrospectively to protect interest that has already been earned. The tax-free treatment normally begins after the funds enter the ISA.
When Is Fixed-Rate Bond Interest Taxed?
Fixed-rate bonds can create unexpected tax bills because interest may be credited, paid or made accessible at different times.
Interest normally becomes taxable when it is received or made available to the saver. If a bond pays accessible interest each year, that interest will usually fall into the relevant annual tax year.
If the account terms prevent the saver from accessing any interest until maturity, several years of interest may become taxable in the tax year when the bond ends.
This could use the entire PSA in one year, even though the interest accumulated over a longer period.
Before opening a fixed-term account, savers should check:
- When Interest is credited
- Whether Interest can be withdrawn annually
- Whether Interest remains inaccessible until maturity
- Which Tax year will contain the payment
- Whether Several accounts are due to mature together
The account’s terms and annual interest certificate will usually help establish when the income must be included for tax purposes.
How Does HMRC Collect Tax on Savings Interest?
UK banks and building societies normally report the interest paid to customers after the end of each tax year. HMRC uses this information to calculate whether an individual has exceeded their available allowances.
Employees and pensioners may have the tax collected by an adjustment to their PAYE tax code.
HMRC may estimate current-year interest using the amount received in the previous year, so the estimate may be inaccurate when balances or interest rates have changed.
People already completing Self Assessment should report their taxable savings interest on their return.
Someone whose savings and investment income exceeds £10,000 will generally need to register for Self Assessment if they are not already registered.
A person who is not employed, does not receive a pension and does not complete Self Assessment may receive a calculation explaining how to pay any tax due.
Savers should retain statements and annual interest certificates from every provider.
If HMRC’s figure appears incorrect, they can ask for it to be reviewed. Tax overpaid on savings interest can generally be reclaimed within four years of the end of the relevant tax year.
What Changes Are Planned for Savings Tax in April 2027?
More substantial changes are planned for the 2027/28 tax year.
The government has announced that the annual Cash ISA contribution limit for people under 65 will reduce to £12,000 from 6 April 2027.
The overall ISA allowance is expected to remain £20,000, allowing the remaining amount to be placed in eligible non-cash ISA investments. Savers aged 65 or over are expected to retain a £20,000 Cash ISA limit.
The tax rates applied to savings income above available allowances are also scheduled to increase.
| Savings tax band | 2026/27 rate | Planned 2027/28 rate |
| Basic | 20% | 22% |
| Higher | 40% | 42% |
| Additional | 45% | 47% |
The PSA amounts are separate from these tax rates. Unless the allowance rules are changed, eligible interest within the PSA would continue to be taxed at 0%, while interest above it would face the relevant savings rate.
As the implementation details may be updated before April 2027, savers should review the confirmed rules nearer the beginning of that tax year.
Conclusion
How much interest a person can earn tax free depends on their total income, tax band and the type of account producing the return.
The usual PSA is £1,000 for basic-rate taxpayers and £500 for higher-rate taxpayers, while additional-rate taxpayers receive no PSA.
Low-income savers may qualify for considerably more through their unused Personal Allowance and the starting rate for savings.
Checking interest across every account remains essential, particularly when income is close to a tax threshold or a fixed bond is approaching maturity.
Frequently Asked Questions
Is the Personal Savings Allowance Per Person or Per Account?
The PSA applies to each individual, not to each savings account. Interest from all relevant taxable accounts must be added together.
Does ISA Interest Count Towards the Allowance?
No. Interest and qualifying returns generated inside an ISA do not count towards the Personal Savings Allowance.
How Is Interest From a Joint Account Taxed?
Interest from a joint account is normally divided equally between the account holders. Each person applies their own allowances to their share, although a different split may apply where beneficial ownership is unequal.
Do Scottish Taxpayers Receive the Same Allowance?
Yes. Scottish taxpayers can receive the same £1,000, £500 or £0 PSA. UK-wide thresholds are generally used to determine the PSA even though Scottish tax bands on earned income differ.
Do You Need to Declare Savings Interest to HMRC?
Banks usually report UK interest directly to HMRC. Existing Self Assessment users must include their interest on their return, while savings and investment income above £10,000 generally requires registration.
Can Savings Interest Push You Into a Higher Tax Band?
Yes. Savings interest forms part of total taxable income, including the portion taxed at 0% under the PSA. It can therefore move someone into a higher band and reduce their allowance.
What Happens If You Exceed Your Allowance?
Only the interest above the available allowances is normally taxed. The rate depends on the tax band into which that savings income falls.
